Last updated: September 18, 2026 — Nexo Legal Tax Team
Quick answer: As of this update, Colombia tax reform 2026 — the reform announced by President Abelardo De la Espriella’s government — has not been formally filed in Congress. The Finance Ministry has confirmed the intention to file it, with September 2026 as the expected window, but without a committed exact date — Finance Minister-designate Miguel Gómez Martínez has been explicit that the bill will arrive “later” within what remains of the year. What is confirmed, with direct statements from the president and his finance minister: the wealth tax would be eliminated, corporate tax rates wouldn’t change, and the revenue target (between COP $25 and $32 trillion for 2027) would come from broadening the tax base, not from raising rates. This page is updated as news develops — if you’re looking for minute-by-minute headlines, outlets like Infobae, El Tiempo, or El Colombiano will serve you better than a blog article. If what you need is to understand what this means for your company in Colombia today, keep reading.
Tabla de Contenido
- ¿Ya Se Radicó la Reforma Tributaria 2026?
- No la Confundas con el Recorte de Gasto de Agosto
- Lo Confirmado: Elimina el Impuesto al Patrimonio
- Lo que NO Cambiaría: las Tarifas Corporativas
- De Dónde Saldría el Recaudo
- La DIAN Pasaría de 15 Impuestos a Solo 3
- El Contexto Fiscal Detrás de la Reforma
- Qué Significa Esto para tu Empresa Extranjera en Colombia
- Qué Sigue: El Camino Legislativo Esperado
- Preguntas Frecuentes
¿Ya Se Radicó la Reforma Tributaria 2026?
No. As of this update, Colombia tax reform 2026 — the reform De la Espriella’s government has been discussing — is still a policy announcement from the Finance Ministry, not a bill filed before Colombia’s Congress. President Abelardo De la Espriella announced the intention during his inauguration speech on August 7, 2026, and since then, Finance Minister-designate Miguel Gómez Martínez has repeated in multiple public settings — including an event with the Development Bank of Latin America and the Caribbean (CAF) — that the government would first execute an administrative fiscal adjustment plan and only afterward take the reform to Congress.
The window most cited by the government itself is September 2026, without committing to an exact date. That means two practical things for anyone reading this in Colombia: first, that everything that follows in this article describes an announced proposal, not a law in effect — nothing below changes your tax obligations for this year. Second, that it’s worth treating this page as a living document — we’ll update it as soon as the bill is actually filed, with the bill number, the concrete text, and the real legislative timeline.
No la Confundas con el Recorte de Gasto de Agosto
Before going further, it’s worth separating two processes that have gotten mixed up in public conversation because they happened almost in parallel. On August 29, 2026, the government executed a COP $21.9 trillion public spending cut by decree — an administrative fiscal-adjustment measure that didn’t require Congress because it doesn’t create, modify, or eliminate any tax; it simply reduces already-approved spending items. We covered that measure in detail, including which agencies were affected, in our article on Colombia’s public spending freeze.
La reforma tributaria de la que habla este artículo es un proceso distinto: requiere un proyecto de ley, debate en comisiones, votación en plenarias de Senado y Cámara, y —si el gobierno consigue las mayorías— sanción presidencial antes de convertirse en norma vigente. El recorte de gasto ya ocurrió. La reforma tributaria, no.
Lo Confirmado: Elimina el Impuesto al Patrimonio
The most-cited point of the reform De la Espriella’s government has announced, and the only one with a direct quote from the president reported by El Tiempo and El Colombiano, is the complete elimination of the wealth tax (impuesto al patrimonio): “The wealth tax will be eliminated,” De la Espriella declared while presenting his government’s economic roadmap.
This is a policy announcement, still without concrete legislative text — we don’t know, for example, whether the elimination would be immediate once the reform takes effect, or whether there would be a transition regime for those already filing under Law 2277 of 2022. It’s also unclear whether the elimination would cover both the wealth tax for individuals (currently in effect with a 72,000 UVT threshold — see our complete guide) and the temporary tax for companies created by Decree 173 of 2026 (see the guide for legal entities) — both remain fully in effect today, and neither disappears until Congress approves something.
Este es, además, el punto donde más fácil es confundirse leyendo noticias sueltas: un anuncio de que un impuesto "será eliminado" no equivale a que ya no debas declararlo ni pagarlo este año. Mientras la reforma no se convierta en ley, el impuesto a la riqueza sigue operando bajo las reglas actuales.
Lo que NO Cambiaría: las Tarifas Corporativas
According to Infobae, citing technical sources within the government, the reform would not touch corporate income tax rates. That’s a relevant detail because it contrasts with the pattern of previous Colombian tax reforms, which typically adjusted corporate rates as their main revenue lever.
Vale una aclaración editorial: circulan en redes y en algunos blogs cifras específicas de una supuesta nueva tarifa corporativa (incluida la cifra de 35%, que ya usa el sistema actual como tarifa general de renta para sociedades bajo la normativa vigente, sin relación confirmada con la reforma). No hemos encontrado esa cifra respaldada por ninguna fuente oficial ni por el propio Ministerio de Hacienda en el contexto específico de esta reforma — por eso no la reproducimos aquí como un cambio propuesto. Si tu empresa recibió esa cifra de un asesor o la vio en otro medio, vale la pena pedir la fuente primaria antes de tomar decisiones con base en ella.
De Dónde Saldría el Recaudo
Si no sube tarifas corporativas ni (aparentemente) las de renta para personas naturales, ¿de dónde saldría el dinero? Según la misma fuente técnica citada por Infobae, la estrategia de recaudo de la reforma tributaria 2026 se apoyaría en tres mecanismos, ninguno de los cuales es "subir una tarifa":
- Broadening the base of filers — getting more Colombians who don’t currently file income tax to start doing so, without that necessarily meaning they’d pay more tax, just that they’d enter the reporting system.
- Eliminating exemptions and tax benefits (“gabelas,” in the term Minister Gómez himself has used) — the government has pointed out that Colombia loses more than 8% of GDP in tax deductions and exemptions, the highest figure reported in Latin America, and that a good part of the reform would aim to reduce that tax expenditure instead of creating new taxes.
- Fighting evasion within the current system, rather than expanding what the system charges.
The revenue target publicly discussed for 2027 sits in a range of COP $25 to $32 trillion. That’s a wide range and not yet official in the sense of “a figure in a filed bill” — it’s the policy goal that has circulated in specialized press coverage, not a number you can cite as final legislative text.
La DIAN Pasaría de 15 Impuestos a Solo 3
One of the details least covered by general-interest press, but one the minister himself has detailed in interviews: the reform would seek to drastically simplify the number of taxes the DIAN (Colombia’s tax authority) administers, from roughly 15 current taxes down to just three: income tax, domestic VAT, and external VAT (the one levied on imported goods and services). According to the minister, 85% of the DIAN’s total revenue today already comes from just two of those roughly 15 taxes — the logic behind consolidating around three is that the rest of that revenue comes from a tangle of minor taxes that, according to the government, cost more in administrative complexity and evasion opportunities than they actually collect.
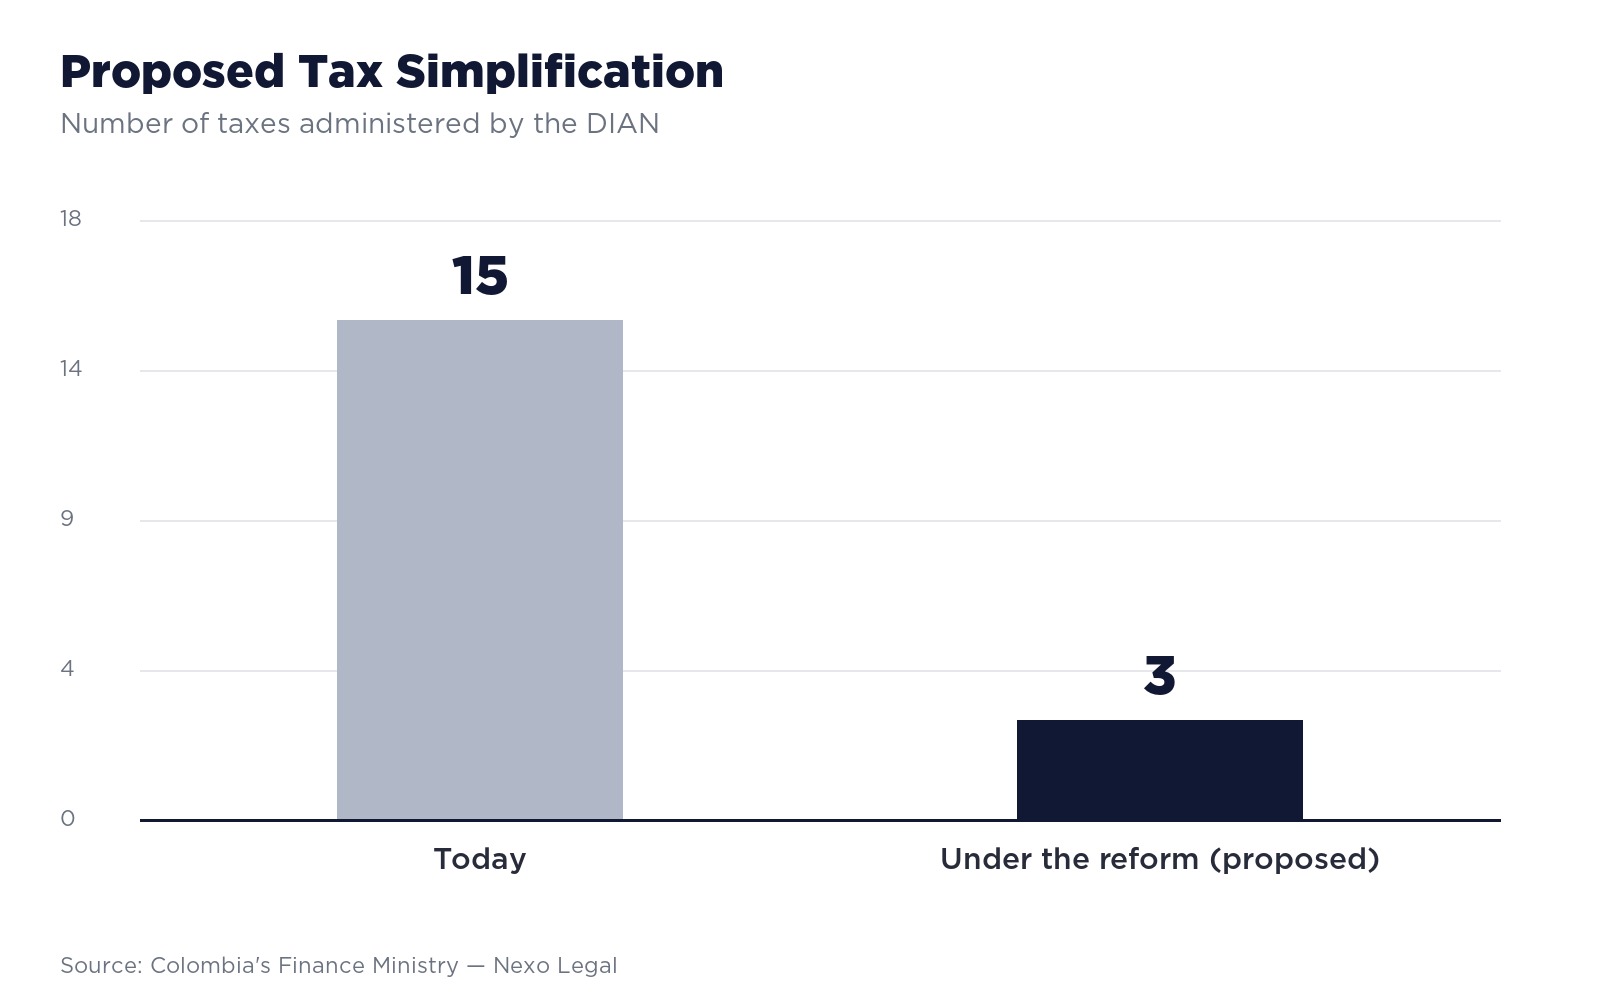
The minister has also mentioned, as a long-term aspiration still without formal commitment, a ten-year tax stability pact — the idea of freezing the tax rules of the game for a decade to reduce the uncertainty that frequent reforms generate in Colombia (the country has had more than a dozen tax reforms in the last two decades). It’s a statement of intent, not a measure with legislative text, but it’s worth keeping on your radar if your company makes multi-year investment decisions in Colombia.
El Contexto Fiscal Detrás de la Reforma
To understand why the government is in a hurry with this reform despite not having the text ready, it helps to see the number driving it: the Autonomous Committee for the Fiscal Rule (CARF), the independent technical body that oversees Colombia’s public accounts, projects a fiscal deficit of 7.4% of GDP by the end of 2026 — well above the fiscal rule’s target. Minister Gómez himself has used a similar figure in interviews, close to 7.5% of GDP, and has spoken of net debt reaching close to 61% of GDP this year, a historic high.
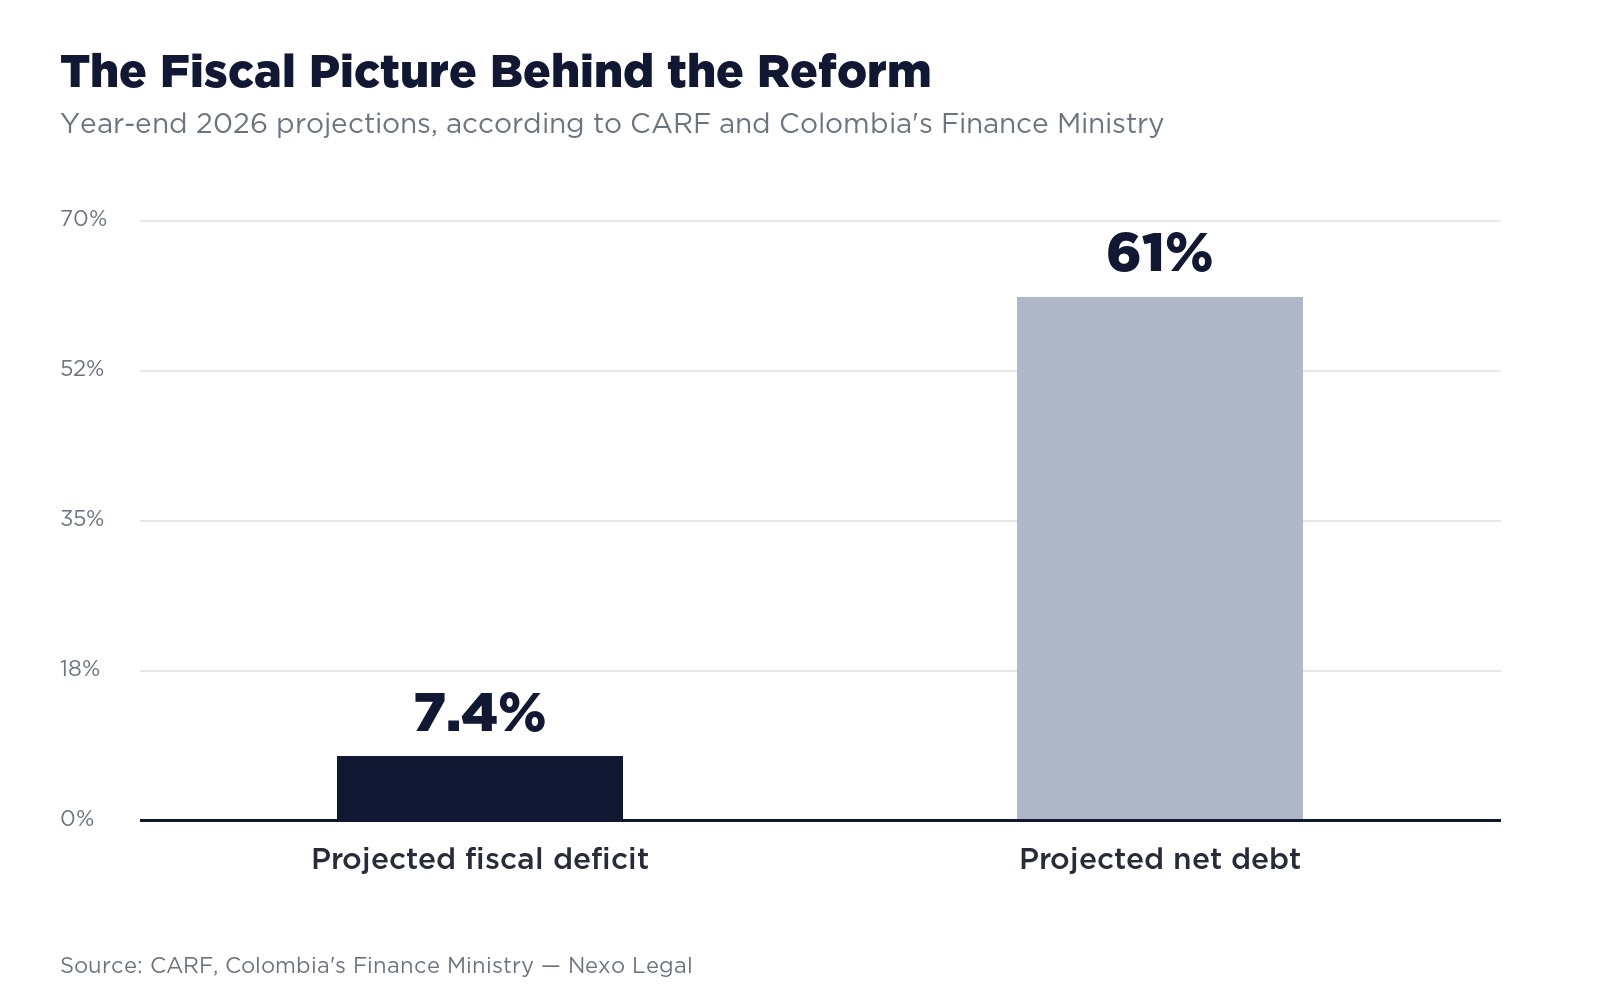
That’s the gap the government says the reform — together with the spending cut already executed in August — needs to start closing. You can review CARF’s own fiscal rule reports directly on the Colombian Finance Ministry’s official site for the underlying figures. This is useful as context to understand the government’s stated urgency, but it doesn’t change anything your company needs to do today — it remains a piece of fiscal context, not a new tax obligation.
Qué Significa Esto para tu Empresa Extranjera en Colombia
Esta es la sección que ningún medio de noticias está cubriendo — y es, en la práctica, la única pregunta que le importa a una empresa con operación en Colombia en este momento. Con base en lo confirmado hasta hoy:
Don’t change anything yet. None of the measures described in this article are law. If your company is calculating tax provisions, budgeting for 2027, or structuring an investment, keep using the current rules — including the corporate wealth tax if your company crossed the Decree 173 of 2026 threshold — until there’s a filed bill with a concrete effective date.
The wealth tax elimination, if confirmed, would be good news with caveats. If your Colombian company is close to or above the 200,000 UVT threshold for the corporate wealth tax, the eventual elimination would free you from a recurring obligation — but probably not immediately, and it’s reasonable to expect some kind of transition regime while Congress finalizes the text.
Watch the “elimination of tax breaks” more closely than the wealth tax elimination. If your company currently uses a specific tax benefit, deduction, or exemption (free trade zone, sector incentives, special income deductions), that’s the part of the reform most likely to affect you directly in the medium term — and it’s also the part with the least public detail so far. It’s worth having your tax advisor start mapping which benefits your company uses today, not to act yet, but so you’re not reading the bill for the first time the day it’s filed.
There’s no confirmed change to corporate tax rates that you should build into projections. If an advisor or a headline tells you otherwise with a specific figure, ask for the primary source before adjusting any financial model.
The ten-year tax stability pact, if it materializes, is the most relevant signal for long-term investment decisions — but it’s at the stage of a stated aspiration from the minister, not a formal proposal.
Qué Sigue: El Camino Legislativo Esperado
Once Colombia tax reform 2026 is actually filed, if the government follows its own stated timeline, the next step would be the formal filing of the bill before Congress, likely accompanied by an explanatory memorandum with more precise expected-revenue figures and concrete text on which specific exemptions would be eliminated. From filing, a tax bill in Colombia typically goes through debate in the joint economic committees of the Senate and House, text reconciliation between the two chambers, and a floor vote — a process that, in recent tax reforms, has taken between two and four months from filing to presidential signature, though each legislative session has its own dynamics.
We’ll update this article with the bill number, the actual filing date, and a summary of the text as soon as it happens. If your company needs specific guidance on how to prepare in the meantime, our tax and accounting team can review your current tax situation and help you identify which benefits or exemptions your company uses today would be most exposed if the reform moves forward as announced.
Preguntas Frecuentes
When will the Colombia tax reform De la Espriella be filed?
There’s no confirmed exact date. The government has pointed to September 2026 as the expected window, but the finance minister has been explicit that it could be later within what remains of the year, after completing the administrative fiscal adjustment plan.
Does the De la Espriella tax reform eliminate the wealth tax?
That’s the intention announced by the president, with a direct quote confirmed by El Tiempo and El Colombiano. There’s still no legislative text saying how or when that elimination would take effect, or whether it would apply immediately or with a transition. As long as the reform isn’t law, the current wealth tax remains in effect for both individuals (72,000 UVT) and companies (200,000 UVT under Decree 173 of 2026).
Does the 2026 tax reform raise VAT or corporate income tax rates?
According to technical government sources cited by Infobae, it would not touch corporate rates. There’s no public confirmation of changes to VAT rates. The targeted revenue would come from broadening the base of filers and eliminating exemptions, not from raising existing rates.
What happens to the 4×1000 financial transactions tax under the De la Espriella tax reform?
It’s been mentioned as a possibility under study for individuals, without a formal government commitment yet. It’s not at the same level of confirmation as the wealth tax elimination.
Does the tax reform affect foreign companies operating in Colombia?
Potentially yes, especially if your company currently uses tax benefits, exemptions, or specific deductions — that’s the part of the reform most likely to affect you, and with the least public detail available so far. Until a bill is filed, no current tax obligation changes.
Is the tax reform the same as August 2026’s spending cut?
No. The COP $21.9 trillion cut was executed by administrative decree on August 29, 2026, and is already underway. The tax reform requires congressional approval and, as of this update, hasn’t even been filed.
Where can I check the official status of Colombia’s fiscal accounts referenced in this article?
The Finance Ministry publishes its fiscal updates on its official press page, which is the primary source we check before updating the figures in this article.
Fuentes: Infobae — "Nueva reforma de De la Espriella no tocaría las tarifas de las empresas" | El Tiempo — entrevista con el ministro Miguel Gómez | El Colombiano — hoja de ruta económica de De la Espriella | Comité Autónomo de la Regla Fiscal (CARF) | Ministerio de Hacienda — comunicados oficiales
Published: September 2026 — Nexo Legal Tax Team. This article is updated as the legislative process moves forward.
Sources: Infobae — “New De la Espriella reform wouldn’t touch corporate rates” | El Tiempo — interview with Minister Miguel Gómez | El Colombiano — De la Espriella’s economic roadmap | Autonomous Committee for the Fiscal Rule (CARF) | Colombia Finance Ministry — official press releases